Weekly Viewpoints on Sustainable Investment by Graham Sinclair with commentary on sustainable investment strategy, changes in the investment markets, and issues of environment, social and corporate governance [ESG] architecture. ESGextra viewpoints are from a growth markets perspective in frontier and emerging markets [see also Visual Notes at esgarchitect.tumblr.com and Tweets @esgarchitect or @SinCoESG].
In this week's note a view on private equity adoption of ESG frameworks and regulators tracking the financial capitalism fingering the commodities business.
Private equity investments may have horizons of 5 - 12 years. Integrating ESG factors has increased as a key hygiene factor for funds raising capital. In my view, ESG in PE may better be understood as a key success factor. Different frameworks for ESG have been introduced, often from collaborative research and co-work. The European-based LPs have a guideline The EVCAHandbook Professional Standards for the Private Equity and Venture Capital Industry (Edition November 2012) (PDF) which describes that: "When making investments on behalf of the Fund, the GP should implement the Fund’s investment policy with due skill, care and diligence and in accordance with the agreements the GP has made with the LPs in the Fund. A GP should be mindful of the responsible investment impact of the conduct of its business and should give due consideration to material risks and opportunities associated with responsible investment factors such as environmental, social and governance (ESG) factors throughout the period of its investment." Most development financing institutions (DFIs) have a framework, for example the IFC (multinational), the CDC (UK) has an industry-leading ESG toolkit for its managers (PDF). DEG (Germany) has also developed an ESG framework, and the PRI disclosure practice guideline (PDF) was published in March 2013.
In conversations lately with private equity practitioners one current view of ESG is that it is about “pain and fluff”. Firstly, the pain of reporting by GPs on the portfolio company ESG and reporting that to the multiple LPs, many of which may be DFIs with their own reporting requirements. Secondly, some PE practitioners discount all the ESG work as too fluffy, too hard to quantify or offer examples of risk or return impacts on their performance. Private equity is seen as a “tax” on doing business and investment, something with little value, and as a cost to the business dealt with by hiring a worker to write up whatever their investors demand to be written. Case studies are needed. The IFC has sponsored some case studies, for example Cogitel in Tunisia (PDF) published with the Emerging Markets Private Equity Association, EMPEA in 2012. Some good examples may also be teased out of reporting by some of the major General Partners (GPs) operating in emerging markets, for example Actis based in London UK which has published some short notes which I have used in lectures. At SinCo we have been shortlisting and collating company narratives and ESG issues components for writing new case studies in PE. We wait for the right sponsor of the new research, and the right forum to present them to. The PRI PE event in Cape Town on 3 October may be one opportunity, or the annual PE events in London and Washington DC focused on the developing world economies. The PRI event is stacking up well with the PRI's Fong Yee Chan working hard with Michelle at AVCA and Erika at SAVCA (and I have been able to help some of the flow and shortlisting keynote speaker candidates this week). More soon.
ESG AS VALUE DRIVER IN PE
The compelling case for PE of “ESG as value driver in private equity” has underpinned much of the publicly-available research from major developmental finance institutions in the past decade. As I have noted before, investment, and investment analysis, in frontier and emerging markets happens across borders of regulations, guidelines and laws. ESG may act as a proxy for advanced due diligence or a marker for absent rules in the marketplace. The virtuous role of ESG has been illustrated in listed equity research of major companies in Europe. Many companies use ratings as a management tool monitoring for example the strengths or weaknesses analysis or as a means to track future trends [SOURCE: The Impact of SRI An Empirical Analysis of the Impact of Socially Responsible Investments on Companies by oekom research, May 2013]. PE deals in growth markets often intersect with building much-needed infrastructure, whether it is building the rail line for a new mine, or the 6,000 housing units for that mining company in some undeveloped patch of the world. Tharman Shanmugaratnam, the Deputy Prime Minister of Singapore was keynote speaker at the CFA Conference in Singapore in May 2013 spoke of the need for long-term investments (e.g. infrastructure), rather than short term or "indecisive" investments, but argued that there is a shortage of asset managers to facilitate these more complex investments. ESG is a value driver in infrastructure deals, shortening the timeline and increasing the possible positive outcomes. An old Harvard Business School Case that I have used as an MBA teaching tool demonstrates that “positive business and investment behavior reduces barriers to accessing investment opportunities and regulatory hurdles to doing businesses, especially in infrastructure deals” [SOURCE: Esty, Benjamin C., Carin-Isabel Knoop, and Aldo Sesia. "Equator Principles, The: An Industry Approach to Managing Environmental and Social Risks." Harvard Business School Case 205-114, January 2007]. Conversations this past Friday at a sunlit sidewalk cafe with the ESG specialist at a major asset owner in emerging markets and a political scientist reminded me of the critical role of the social factors. With the large governance and environmental footprint, it is not surprising that large infrastructure deals attract heavy-duty due diligence from analysts and investment committees. But with great scrutiny, the role of the social factors - how communities are engaged, how the stakeholders are not corrupted, how the social license to operate is renewed and respected - may become increasingly the key driver.
THE DIRTY FINGERPRINTS OF FINANCIAL CAPITALISM ON SHINY ALUMINUM
The asset management industry is going through some tough times as consolidation plays out. For example, IPE reported in June that "AUM growth at 10 largest fund managers outstrips sector", with asset increase of €1.2trn sees and globally, the 10 largest institutional managers were responsible for €12.8bn in assets at the end of December 2012. Elsewhere BCG’s eleventh annual Global Asset Management report reports that “[a]ssets and profits both nearly returned to pre-crisis levels. Still, the asset increase was driven largely by rising markets—not the flow of net new assets, which was modest.” As financial services companies seek yields and uncorrelated returns, so they are broadening their proprietary activities to parts of the real economy. Financial capitalism pervades the real economy. Unfortunately, it seems major players have been bending the rules, as a New York Times investigative report has revealed (THE HOUSE EDGE: A Shuffle of Aluminum, but to Banks, Pure Gold By DAVID KOCIENIEWSKI Published: July 20, 2013). Intermediaries have a place in making markets liquid. Regulators have first place in making them efficient, fair and/or transparent, preferably with a self-regulatory efficiency to enforcement with sanctions overlay to be flexible. And let's price the carbon costs to make sure every cost gets reflected, especially when shuffling metals. And above all, the story is another argument to pay for good quality, long-form journalism that makes it possible to write up these stories. Even as the fate of “Fabulous Fab” (SEC won 6/7 counts of the civil fraud suit against former Goldman Sachs Vice President Fabrice Tourre) played out 4 August some five years after the CDO-driven meltdown led to the global financial crisis, the WSJ reports ["LME, Goldman Sued Over Aluminum Warehousing"] that regulators have now named Goldman Sachs and LME in the lawsuit targeting anti-competitive and monopolistic behaviour in the warehousing marketplace for commodities. Sustainable investment is as much about returning good yields on the investments, as in the way those yields are earned. Its the principle of the investment approach. Will this cause Goldman Sachs et al to review their GS Sustain ESG metrics they report on..?
Do good work on sustainable investment that matters.
Graham Sinclair
@esgarchitect
linkedin.com/in/grahamsinclair
Skype: graham_sinclair
SinCo - Sustainable Investment Consulting
SinCo designs ESG architecture for long term sustainable investment that matters.
www.sincosinco.com
@SinCoESG
Based on my work, experience and interactions, all views and opinions expressed are those of the author and do not reflect the named individuals, institutions or SinCo, it's clients or services providers. No mention suggests endorsement. This commentary does not constitute investment advise. Issued by SinCo to professional investors and stakeholders for information only and its accuracy/completeness is not guaranteed. All opinions may change without notice and may differ to opinions/recommendations expressed by other business areas of SinCo. SinCo may maintain positions and trade in collective investment instruments referred to. Unless stated otherwise, this is not a personal recommendation, offer or solicitation to buy/sell and any prices/quotations are indicative only. SinCo may provide sustainable investment architecture and other services to, and/or its employees may be directors of, companies referred to. To the extent permitted by law, SinCo does not accept any liability arising from the use of this communication.
8:30pm Saturday 28 March 2009 and NOT so dark at the bottom of Africa. Nor in Sydney nor London for that matter. Earth Hour South Africa, as the photo suggests, was looking a tad too bright! What change did we observe in our unscientific survey from Table Mountain overlooking the Cape Town CBD? The Cape Town provincial government and city offices were dark [yes, there may be other explanations than energy saving!]. The only visible change at 20h30 CAT [Central African Time] was the ABSA building logo going dark, perhaps because ABSA [JNB: ABSP] is now majority owned by Barclays [LON: BARC], and the degree of coordination was good.
What “beacons” kept shining vaingloriously under southern skies? From our perspective, not much about the city changed, with the amber glow of incandecent and the blu-ish light of neon strung around CPT as usual. After the speeches by African politicians and with South Africa representing Africa into the G20 and climate change negotiations heading to Copenhagen in December 2009, one hoped for major Parliamentary action. Underwhelming…What of the corporate players? Most easily spotted – there were others we did not spot – were some brands making the wrong statement in the African night sky:
FNB [First National Bank], which uses an iconic African acacia as its corporate identity
Nedbank, a billboard for the “green bank” storeys high downtown, which figures, because they had ZERO Earth Hour coverage on their busy wesbite.
Oops?! Nedbank [JNB: NED] must have been feeling awkward come Monday, what with having pitched their positioning on the JSE SRI Index in April 2008, hosting the Green Mining Awards, and being the bank with the affinity program for customers tied to WWF SA called Green Trust. Motivating a major global financial institution to action is a logistical mountain, as JP Morgan Chase Earth Hour PR illustrates in defining what it can and cannot do. Reminds me of the story from a mate in Corporate Responsibility at ANZ bank in Australia. As head of the Earth Hour project around 2007 she had plans in place to cut lights in the large ANZ [OTC:ANZBY; ASX: ANZ] headoffice building in Melbourne BUT could not get her facilities people to guarantee the huge neon signage crowing the building to go dark. Unperturbed, and in superb Aussie “can-do” fashion, she had on stand-by a colleague or two with a large hatchet and some rubberized boots! No way that light was shining at 8:30pm! One gets a sense for the drama watchng the video of Earth Hour Cape Town mayor Helen Zille doing the big switchoff, and the relief of "oh, it worked!". Things have moved on sufficiently that this year the ANZ-sponsored ANZ stadium, a major in Australia, voted to switch off its external branding lights. See the list of participating Australian banks.
Woolworths supports Earth Hour: For one hour, millions of people will switch off their lights across the globe in support of Earth Hour to raise awareness on saving energy. Saving energy is an important part of our Good business journey and we encourage all colleagues to participate by turning their lights off for an hour. Earth Hour is a World Wide Fund for Nature (WWF) initiative. On 24 and 25 March you can change your incandescent light bulb for an energy saving light bulb, courtesy of Woolies and Eskom. This will save you money and help to reduce energy usage. This is a small way for each of us to participate in our Good business journey. Woolworths is targeting a 30% relative reduction in energy usage by 2012. When: 24 and 25 March from 09:00 - 13:00 Where: Woolworths house, foyer. Please note that we can only exchange a maximum of five light bulbs per person. Remember to support Earth Hour on 28 March from 20:30 to 21:30. P Consider the environment - do you really need to print this email?
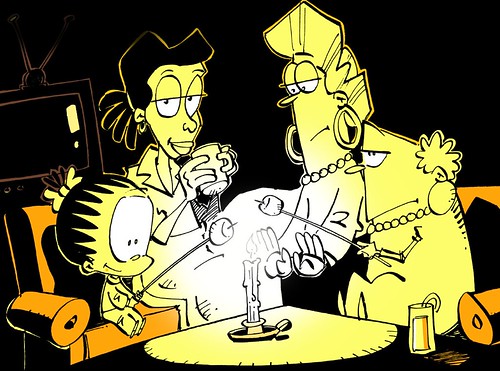
Earth Hour is one of those tipping point type efforts, the ones where a small item at the right point of leverage creates some kind of systemic change. Gladwell made it common jargon with business types early this century. Think of the first time you saw a cellphone that was more mobile telephony than brick or a music player as seamless as the second generation iPod. In the same category we recommend to you Nudge. The current thinking person's book – Nudge: Improving Decisions About Health, Wealth and Happiness [good timing, boys!] – relies less on regulation but suasion as a driver. Earth Hour, one of the better things to come out of Australia, aims to use just an hour as a window to a different future, highlighting the a raft of environmental issues by reversing the glaring trend to burn energy to light up the planet [roasting marshmallows as in Madam & Eve is optional!, see cartoon above]. WWF is the enviro NGO which is held in high esteem globally, is behind the idea since the Australian affiliate moved onto it in 2007. WWF helped popularize it in the US, Europe and Africa through local affiliates. Even Brunei joined in this year with mosques covering ecology in the Friday sermon. Brunei was the sixth largest per capita CO2 emitter in 2004, and always worth a punt in your geography quiz - Q: which continent is Brunei on?The first-ever OPL cohort covered Earth Hour in our review of international awareness and advocacy tools on the inaugural WWF One Planet Leaders programme in Switzerland in 2007/8. Earth Hour 2009 aims to "reach more than one billion people in 1000 cities around the world, inviting communities, business and governments to switch off lights for one hour at 8:30pm on Saturday March 28 and sending a powerful global message that we care enough about climate change to take action".
Chicago Tribune included some beautiful shots, see Bern cathedral after 8:30pm CET. The ultimate photo-op would not be darkness at night, a reversal of the classic artificial “world at night” photo from the NASA project to plot urbanization which we often use to describe systemic approaches and regional differences to sustainability+investment and sustainable development. That photo replaces thousands of words. It reflects the sustainable development footprint and challenge, as well as being useful to quickly pinpoint critical footprints for Sinclair & Company in SA, USA and Switzerland. It is a little harder to pinpoint Harare, for example. Earth Hour works on local time, so the rolling blackout kicks in according to international timezones [an arcane system worthy of another blog another day] from 8:30-9:30pm local time.
Things Go Bump in the Dark
Certainly the WWF and Earth Hour South Africa team had great marketing reach, and some big brand names as participants. In Cape Town, the iconic Table Mountain went dark – in the same way that peer emerging market major Brazil had the lights on the Christ statue in Rio de Janiero go dark - see some great photos and comments on GlobalVoices. Unlike the Sydney Opera lights apparently, bad form, Oz. Pop radio DJ Fresh on 5FM had some useful suggestions for the young and virile with a dark Saturday night hour to kill.
Even the most exclusive CPT eateries interrupted diners to explain the lights would be cut for the hour – but that’s never a problem where an extra candle as to ambience and the grill is gas-fired. In the streets the “grass-roots” approach in this emerging market as always relied on the lamppost signs strapped up pitching the idea, in between the election posters. Random support came through using the local Idols to spread the word, as the SA Property blog did. The Earth Hour Facebook group had 859,516 members, and blog Greenmarket covered the myriad other electronic marketing approaches [never did get the BB download though...] including photo stream on Flickr. With all this global coordination reminding me of the all-time greatest worldwide brand – Y2K – one wonders how the branding specialists will one day hence come to rate Earth Hour as a global brand?
The UN SG endorsed the effort [but here the earlier comment regarding public offices and darknesses echoes[!]] and one of the fine old twentieth century institutions, Baden-Powell’s Scouts had action at community level. But what difference does it make? As a global phenomenon it was open to interpretation. In South Africa the Mail&GuardianThought Leadership blog [the editors feeling a little lofty the day they launched it, mmm?] the hopes were high, but Bridget McNulty’s view from Signal Hill matched ours from the slopes of Devils Peak: underwhelming. In the most environmentally-sensitive city on the continent. Check some of the Comments to Bridget's posting Earth Hour: A Little Underwhelming... which reflect the ambivalence to this form of social action, and in the contradictions in creating change which in itself uses energy. Even 1970s era environmentalists at National Post add some contra-wisdom.
Enter the Investors
My interest as always is to probe: where are the investors? No, one will never find a line-item for compliance with Earth Hour in the Green Century Mutual Fund from Boston, or the GS Sustain index from London, nor the RIAA certification. Not even in the WWF International’s own green investment product run from international headquarters by Chiew Chong, the Living Planet Fund, offered for sale as an OEIC out of Luxembourg to European clients. Australian industry website Ethical Investor posted the event, But a rough poll of some leaders in investing integrating ESG factors had at best an ad-hoc, personal approach, as opposed to a coordinated, strategy one would expect from sophisticated knowledge-based service industries. A simple list of investment/financial Earth Hour participants in Africa were:
ABSA
Coris Capital
Coronation Fund Managers
Discovery
Investec
Liberty Group
Metropolitan
Momentum
Nedbank
Old Mutual
Sanlam
Santam
The Earth Hour event juxtaposed timeously with the Principles for Responsible Investment [PRI] annual assessment submissions due 31 March 2009. As my experience reflected when working with the PRI annual assessment 100-odd questions on making the six principles of the PRI happen, it is easy to put up some aspirations with guidelines and waving a flag. Many of the PRI’s key signatories share the discomfort. It is much harder, but yet so much more impactful, to measure the outcomes and net impact of the driven behaviour. Earth Hour is just an event. But maybe it should be a line-item along with the other 100 questions for investors. It does at least offer the advantage over the 100 other data-points: complete transparency and immediate accountability in real-time. Inaction leading to reaction from consumers, observers, and investors, with reputation sensitivity driving future action.
Earth Hour, as some beautiful photos attest, was no doubt a success. WWF has done well, and partly by not hogging the spotlight putting the issue above the WWF brand. It is obvious that the symbolism is not enough, as BusinessWeek suggests through it's guest commentator, with interesting Comments. Earth Hour points participants toward the major Copenhagen conference and the Species Report. It is but a moment, not even 10% of a day/night cycle. The next obvious anniversary date upcoming is Earth Day. More symbolism and action/inaction sure to follow. Like all ceremonies and rituals, sometimes useful for impact, but at least useful for planning the diary.
Will Earth Hour 2009 nudge the thinking further along the learning curve, and will the youth remember it when they next come to make investment decisions?
In the week that began with Citi [C] becoming the US government's latest shareholding, JPMorganChase [JPM] was pitching their core competency as a lender, and Goldman Sachs [GS] was looking to stretch their sustainability advantage branding their research and investment products. JPM was busy offering a full page advertisement in WSJ Eastern edition A5 Tues 25 Nov pitching to the WSJ readership on their commitment to lending [“Our Business Is Lending. And That’s Exactly What We’re Doing”], including “in a responsible way”. Yes, I can only imagine what my mate who taught me how to build a BS filter for company ESG claims, the KLD research director in Boston, will say about that one!
Goldman Sachs was taking the front foot in the FT Mon p.3 with the first above-the-line hardcopy advertisement I have seen for GS Sustain, a fair advertising budget commitment to go above-the-line. Of course GS hedged bets by burying the ESG lead in the body, the sub-title “innovative thinking finds innovative companies”, and one has to mine the paragraph further for “a unique global equity strategy that brings together ESG (environmental, social and governance) criteria, broad industry analysis and return on capital to identify long term investment opportunities”. But GS now fronts their homepage with GS Sustain. Clearly someone is taking a big bet, and perhaps with freefall markets, a good time to try something completely different.
GS Sustain has a colourful history. It's strong underpin is from the GS sell-side in London via the work dating back to 2003 of Anthony Ling in the Energy Equity Research team, and then taken forward by Sarah Forrest, Marc Fox and colleagues. Sarah is now an Executive Director for Global Investment Research. After finally establishing a coordinated framework in early 2007 – GS Sustain – which launched to plaudits from the usual UN Global Compact types and affiliates in Geneva last July, the GS Sustain brand has been slowly building. Like IBM, no presenter looks dumb when quoting GS – a false security to be sure – but expedient for now. Indeed, in my MBA865 seminar at Kenan-Flagler Business School, Sustainability in Investment Strategy at Chapel Hill last week, one of the most informed students referred to “it’s Goldman Sachs!” as the GS halo in the ESG space proves to light the way for less skeptical inquiry of how sustainability plays in. Clearly GS benefits from being one of the two last i-banks standing, [mostly!], and may push for competitive advantage on sustainability matters in the FT, the print daily which positions itself in US as more global than the WSJ or NYT Business Day as a major business daily. Companies, as they do with any positive third party assessment, but especially when it is a major i-Bank brand, are only to happy to tout their standing in any competitive assessment, such as BG Group[LON: BG] a natural gas company.
I was first alerted to the new GS Asset Management product built off the GS sell-side’s GS Sustain framework in Manhattan at the Sustainable Investing 2008, People. Plant. Profit. on September 23-24th, 2008 at The Harmonie Club, New York City. At that time the product was available offshore only, but now institutional US clients may access it. The conference was hosted by Financial Research Associates, LLC for the first time, as a new conference publisher entering the sustainability space, with assistance from SIF.
In the next two weeks I will be having a more solid look at GS Sustain GSAM product as forward planning for when it has run a year at least and we may start recommending the strategy from an informed understanding to the benefit of asset owners and multi-managers. I like that GS Sustain is in the game, for sure, but a close examination of some of the underlying criteria makes me cautious based on my past experience of ratings that are built on "box checking". The framework looks good, but underlying data, and assumptions like memberships of an initiative or international organization sending signals about sustainability, may be sub-optimal. I am cautiously positive, and our recommendation at Sinclair & Company to investors is to observe closely, and stress-test the ideas before becoming convinced. I have not reviewed the strategy in detail since hearing about it in late Sept, partly because the most impressive aspect of the Sustainable Investing 2008 event had me moving to other thinking. Other than Tim Smith’s usual excellent chairmanship [when not chairing SIF, he is in Boston as Senior Vice President at Walden Asset Management], was the compelling speech by Joe Keefe CEO of PAX over lunch, one of the best expositions on where ESG/sustainability investment is in 2008, and where it may go, an extract of which is here.
And of games, well, it just would not be right to cover emerging markets and London in the same story, and fail to mention Saturday's smashing game the Springboks played against England which CNN titled "Springboks Thrash England at Twickenham". Rugby, like life, rewards grit as well as grace, with patience a coaching watchword lately. So comprehensive, the Brits found time to boo their team. Yikes! The tackles, the tenacity and the touch South Africa showed against England in their backyard, racking up the Roses’ biggest ever loss at home, was a fresh reminder of the entrepreneurial and rugged nature of the boys from the bottom end of Africa.
Sarah is an Aussie, so she would have enjoyed it, and the headliner from The Australian "Springboks Outclass England at Twickenham". The boys from Goldman are credited with the BRIC monikercoined the term ‘BRIC’ in our Global Economics Paper, ‘Building Better Global Economic BRICs’, published on November 30, 2001. Maybe they had seen Bakkies [“bricks”] Botha make a tackle sometime before, like the try-saving one he made on Saturday? [sidenote: should every rugby player hope for a wikipaedia entry?!]. Yes, I know, South Africa has the ability to play sublimely one week [has Australia recovered from 50-odd thwack at Ellis Park, their biggest ever Test loss?] to the slack - only one Tri-Nations title in all these years. But as I pitched at the Paris UN PRI Board meeting in Nov 2007 - to the sullen looks from the Englishman directly after Springboks won in Paris [and a smile from the Frenchmen] - nice to see EM on top. A small smile for EM slips out when running through the scoreboard from Saturday: Emerging Markets 42 vs. Developed Markets 6.
The England coach called it “brutal” and “a lesson”. Pretty much sums up the financial meltdown for EM and the rest of the world too, and the bleak '09 outlook. Enough said.
It has been a rough spring in emerging markets in the South [this photo is from April, obviously]. The emerging markets, as simplified and represented by the BRICS moniker [Brazil, Russia, India, China, South Korea and South Africa], have been bounced out the back of the financial services meltdown wagon. The benchmark indices catch you up on the story quickly, and the forex cross-rates quickly offer the impact - Brazilian ranches, Russian dachas or South African wine estates are cheap right now for payers in USD! Yes, as a fixed income manager mate in Cape Town will attest, this creates a serious challenge for his vacation strategy – which weakened forex rate best matches the exotic destination he would like to visit in January?!
“…expect GDP growth in the BRICs to be lower this year than last, the structural changes in these economies-and indeed in the world economy-are likely to make the impact of the global slowdown less severe than in the past…one of the key underpinnings of the BRICs' strength: capital flows”
BRIC is the original acronym coined by the GS EM team in NYC, although BRICS is my preferred acronym, and ChIndia the population-weighted current favourite on CNBC. And whether local or foreign, how tough the investment forecasting game is may be illustrated by reflecting on conclusions like…
“Overall, the deterioration in capital flows that we anticipate this year is manageable, and we remain bullish on the BRICs currencies. We expect appreciation of 8% against the USD in China, 4% against the USD/EUR basket in Russia, and 5% against the USD in India. In Brazil, we think the Real could strengthen over the next three months, but it is likely to weaken later in the year.”
The personal finance regulars in WSJ Tues covered the sad EM tale with their “SmartMoney” screens, from being up 50% p.a. in China in ‘06 and Brazil in ‘07, now down about the same magnitude in ‘08, with the Fidelity Latin America fund down -65.6% YTD @ 20 Nov. Yikes! No wonder Fidelity is letting go staff in BOS to trim expenses. Interesting as always to note the pricing – of the no-load funds, the passive tracking option from Vanguard [Vanguard Emerging Markets Stock VEIEX] proves to be cheapest as always, with 40bps annual fee. And like Wal-Mart soaring in these tough depression days as consumers know where to purchase lots of cheap stuff, maybe Vanguard will gather assets even as the regular 401k contributions have to go somewhere. But retirement advisors, a growing advisory service category according to FRC, will need to be longer-term orientated to recommend emerging markets to US clients in 2008. Like Africa, EM is not for sissies! Donald Hanna, MD and Global Head of Emerging Markets Economic & Market Analysis at CITI in New York, offered a bleak look at where EM may be for ‘09 in a presentation in BOS last Thurs. His take on Brazil and South Africa seemed fair...hard times ahead.
Standard Chartered, a bank and a solid emerging markets play based on their strong network in Middle East and Africa, is raising around USD3 bn through a rights issue and just hosted an Investor Trip to its banking operations in India, Abu Dhabi and Dubai from 17 to 20 November 2008. Standard Chartered has a network of over 1,750 branches and outlets in more than 70 countries across the Asia Pacific Region, South Asia, the Middle East, Africa, Europe and the Americas and employees about 75,000 employees from 115 nationalities. Their branding tied to marathon running and cricket hints at their EM exposure. Although without an in-house money manager [I pitched them on joining the PRI in EM project back in Dec 07], nor with direct exposure to toxic US mortgage assets or developed markets financial services, the tough times ahead imply the need for more capital on hand. STAN has some good programmes in EM, as the programme head Mariannne Mwaniki covered last July at for the Global Compact 4th annual Communication on Progress (COP) workshop at the Palais des Nations in Geneva.
Many EM banks did not have direct exposure to sub-prime. But similar to our experience in the South African market, where banks and money managers were prevented from reckless exposure by capital restrictions allowing only 15% offshore investment and hence no major exposure to the developed markets contagion, the resulting flight from risk – perceived or real – has smacked the forex rates and JSE as investors pulled back cash from every accessible liquid markets. At STAN I like some of the work done to play in local communities, for which STAN has won acclaim. STAN have used the IFC Equator Principles guidelines on STAN project finance in developing countries since their inception and adopted the revised Equator Principles 2 (EP2) in June 2006. I think EP2 is solid, but I know NGOs like Banktrack.org have their doubts, and I look forward to research to check in on progress on the ground from a former Boston College Center for Corporate Citizenship colleague now at HKS.
In the STAN [Standard Chartered PLC, LON:STAN] core banking business, the opportunity “at the bottom of the pyramid” makes sense: improving access to sustainable financial services plays an important role in empowering people, both socially and economically, and grows the STAN client base. In Q1 '08 STAN’s Robert Tacon was elected to head UNEP FI, the UNEP/financial sector initiative that organizes conferences and publishes pamphlet [see basic PPT from Seoul July '08 here]. It was a pity when he left in later this year, although I am not sure really what happened there… STAN’s above-the-line campaign, including the FT US print on p.8 of Mon 24 Nov US edition, makes clever connection to their business + community approach with a board room morphing into a well. Solid brand positioning is their reward for a clear marketing message.
STAN is not in Eastern Europe, Latin America, nor the Far East. When we last spoke in his role in sustainability at STAN, Rob's view was that it was:
Look at what organization sets itself as objective, for example, is environmental and social factors on the agenda?
And if it is, then how is it implemented?
His opinion was that companies that take into account ESG will do better. The aim of training is to show why ESG is important, as a long run issue, while in the short term is about reputation. But the benefits to organization need time to manifest itself, it also depends who they are investing for. In EM, he confirmed, it is very hard to convince people, far more difficult to crack sustainability in many respects.
At least STAN has not copied Barclays which has basically shattered investor confidence by rushing to the “Medici” in the Middle East for cash, apparently GBP 7bn [USD 11bn], rather than UK government money with strings. STAN is tapping existing shareholders first. Barclays, which itself bumped up EM exposure by taking a controlling interest in ABSA, one of the big four in South Africa, managed to upset all shareholders with their plan. But being stuck up a creek without a paddle, the investors apparently agreed Mon to let Barclays proceed, knowing that the whole Board is up for a vote next April. Do not be surprised when the door swings the other way at the first next opportunity. George Dallas, the director of corporate governance at F&C Asset Management [and former head of S&P’s CG effort before that was frittered away so needlessly like other ratings agencies], was piqued on Mon. F&C had “reluctantly” voted for the capital raising, but George was quoted as saying "We think that this amounts to a clear and egregious abuse of pre-emption rights. We object that the consequences of voting against this particular transaction would make a bad situation worse". F&C sees "environmental, social and governance [ESG] issues as fundamental drivers of long-term corporate performance, a principle that is central to F&C’s philosophy as an asset manager", and sell their responsible engagement overlay [REO] service.
The Barclays meeting was a fun example of live capitalism right up there with Gordon Gecko’s Wall St address. Shareholders at the 200-strong gathering were still asking questions after 2 hours when Marcus Agius, the bank's chairman, closed the meeting and one shareholder was apparently checked by security guards as he approached the stage. Chairman of Barclays? It too is not for sissies! SRIX.GS